Farm Finance
Buying a farm ute: a finance checklist before you go to the yard
Pre-approval, dealer finance versus a broker, private sales and GST. What to sort out before you buy a farm ute in New Zealand.
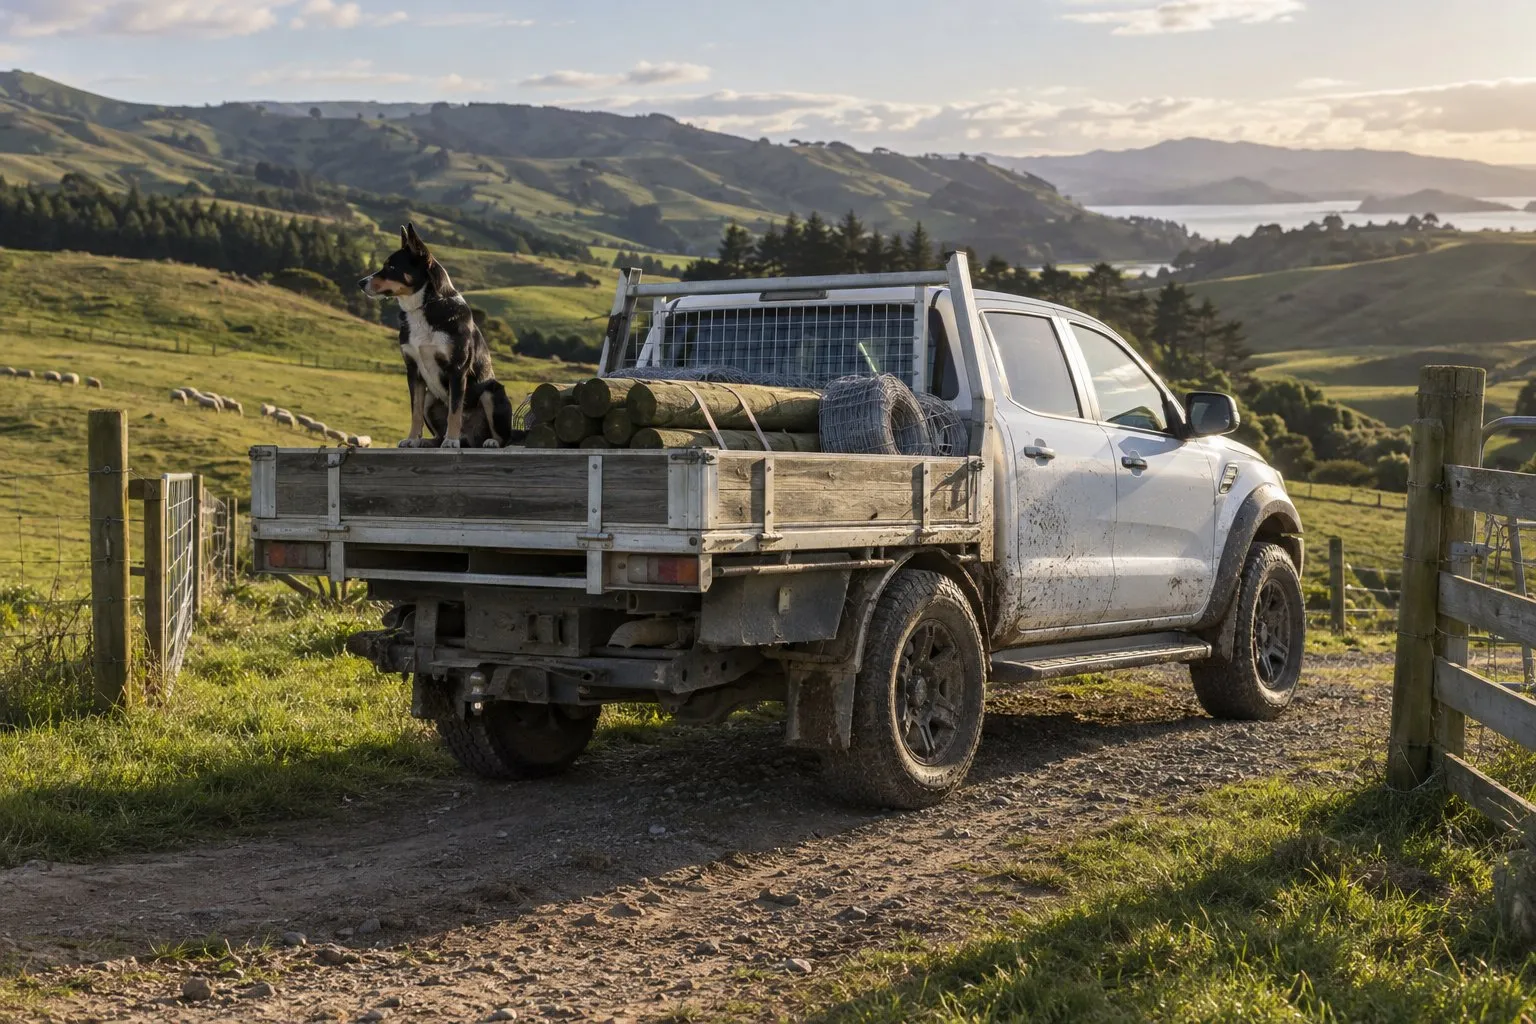
A ute is the hardest-working vehicle on most farms, and it is often bought in a hurry when the old one finally gives up. A little preparation on the finance side means you negotiate on the ute, not the loan.
1. Get pre-approved before you look
Pre-approval tells you where you stand before you start looking. It means you can walk into a yard, or reply to a private listing, knowing what you can spend. Most pre-approval requests come back within one business day, and starting one has no impact on your credit score.
2. Know how you are buying it
Tell the lender up front:
- whether you are buying personally or through the business
- how the business is set up (sole trader, partnership, company or trust)
- whether you are GST-registered
It changes which lenders suit you. How GST and depreciation are treated on the ute is a question for your accountant.
3. Have the paperwork ready
For self-employed farmers this is usually three to six months of business bank statements and your latest IR3 or financial statements.
4. Compare the dealer offer
Dealer finance can be convenient, and sometimes it is the best deal on offer. Before you sign, check four lines: the rate, the fees, the term and the total you repay. Then ask a broker to put it beside the alternatives. Sometimes the dealer offer is the best one. Sometimes it is not.
5. Buying privately
Private sales can be financed too. Send the listing or the seller’s details through and the lender will tell you what they need, which normally includes a check that no money is owing on the ute.
6. Think about the whole cost
A longer term lowers each repayment but costs more interest overall. Work out what you can comfortably carry in a quiet month, not just a good one.
Do you need a deposit?
Not always. Whether a deposit is needed depends on you, the ute and the lender’s criteria. Where you can put one down, it usually helps your rate.
Next step
Start a pre-approval in about 60 seconds, or call Tyler and talk it through. New or used, dealer or private, every application is assessed case by case.
Ready when you are.
Sixty seconds. No impact on your credit score. No commitment. Tyler will be in touch fast, usually the same day.