Farm Finance
Can you finance a quad bike or side-by-side in New Zealand?
Yes, quads and side-by-sides can be financed in New Zealand. How dealer finance compares with a broker, what lenders ask about used machines, and what to sort out before you buy.
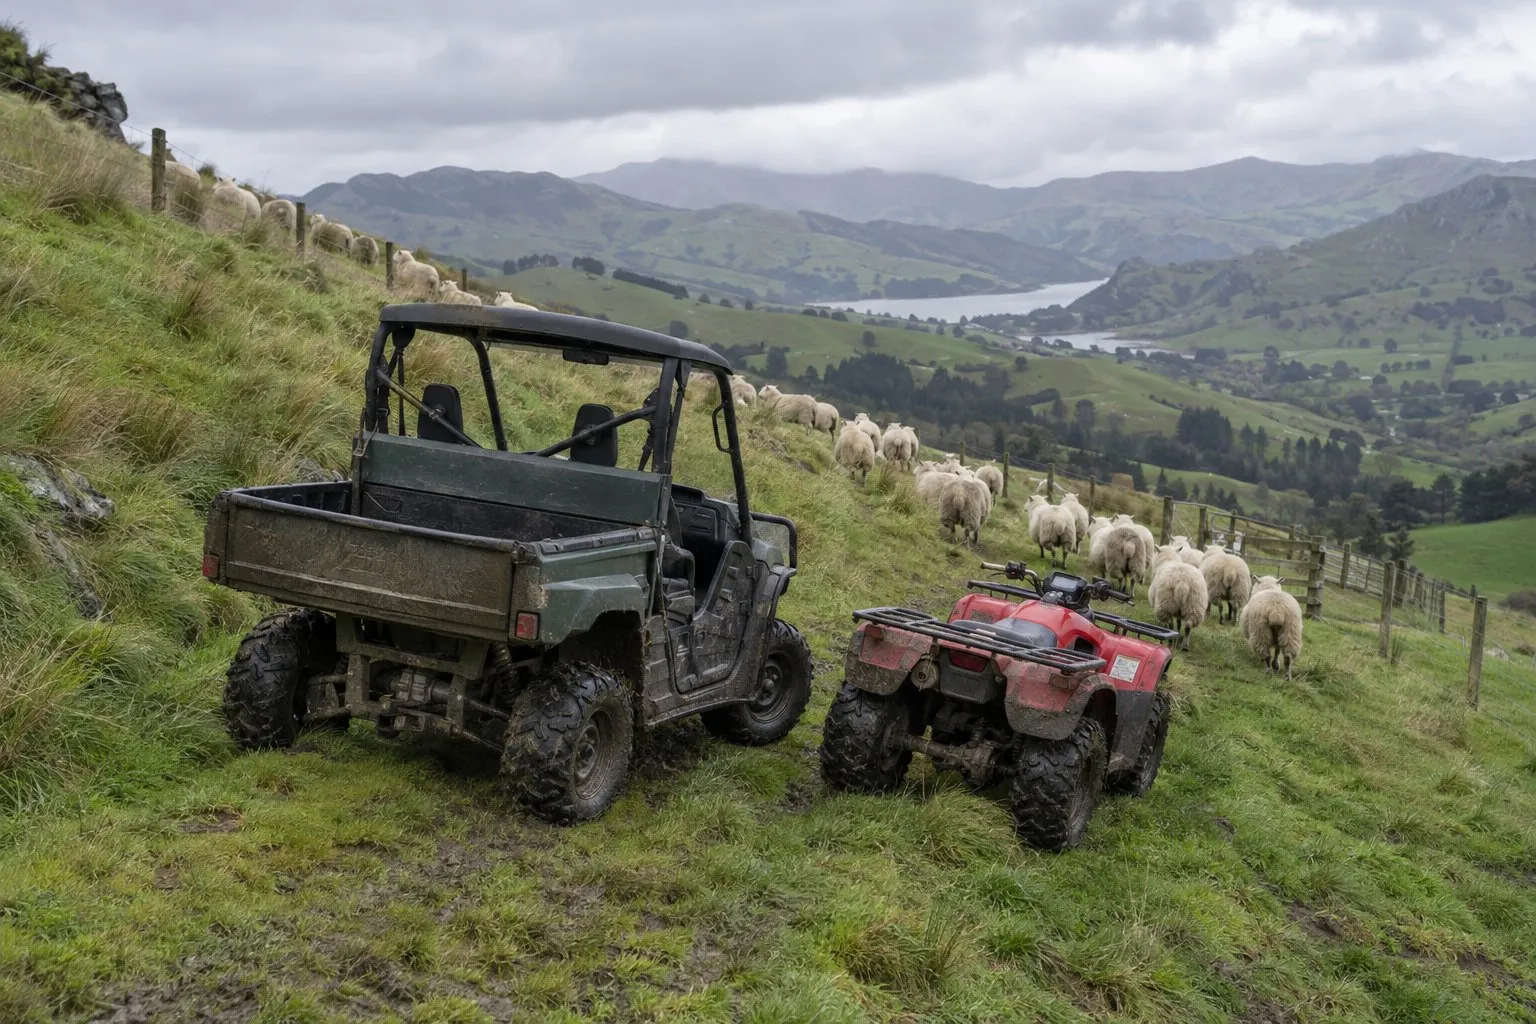
Yes. Quad bikes and side-by-sides are financed every day in New Zealand, most often through the dealer at the point of sale. Whether that is your best option depends on whether the machine is new or used, where you are buying it, and how your income looks.
Dealer finance on a new machine
Most of the big quad and side-by-side brands have finance available through their dealers, and promotional deals on new machines are common. If you are buying new and the promotion suits you, it can be hard to beat.
Things to check before you sign:
- whether the deal needs a minimum deposit or a set term
- the fees, not just the rate
- the total you will repay over the life of the loan
Buying used or privately
Promotional deals rarely apply to used machines, and a private sale has no dealer finance at all. This is where a broker is most useful. One application goes to specialist lenders who will consider a used quad or side-by-side, and you get a straight answer about what is possible.
Lenders will usually want to know:
- the make, model and year
- the price and who you are buying from
- that there is no money owing on the machine (normally checked for you)
There is no blanket age limit. Each machine is assessed case by case, so it is worth asking before you agree a price.
Quad or side-by-side?
That is a safety and workload decision before it is a finance one. WorkSafe New Zealand publishes guidance on choosing the right vehicle for the job, covering terrain, loads, passengers and rollover protection. Read it before you buy. The finance application is the same either way.
If your income is seasonal
Farm income does not arrive like a wage. Lenders who work with self-employed borrowers can assess your business bank statements and financial statements across the year rather than one month. Repayments are regular, so they need to fit your quiet months as well as the good ones.
Do you need a deposit?
Not always. Whether a deposit is needed depends on you, the machine and the lender’s criteria. Where you can put one down, it usually helps your rate.
Next step
Send us the machine details and roughly what you want to spend. Tyler will tell you which lenders it suits, usually within one business day, with no impact on your credit score to ask.
Ready when you are.
Sixty seconds. No impact on your credit score. No commitment. Tyler will be in touch fast, usually the same day.