Farm vehicle and machinery finance for New Zealand farmers
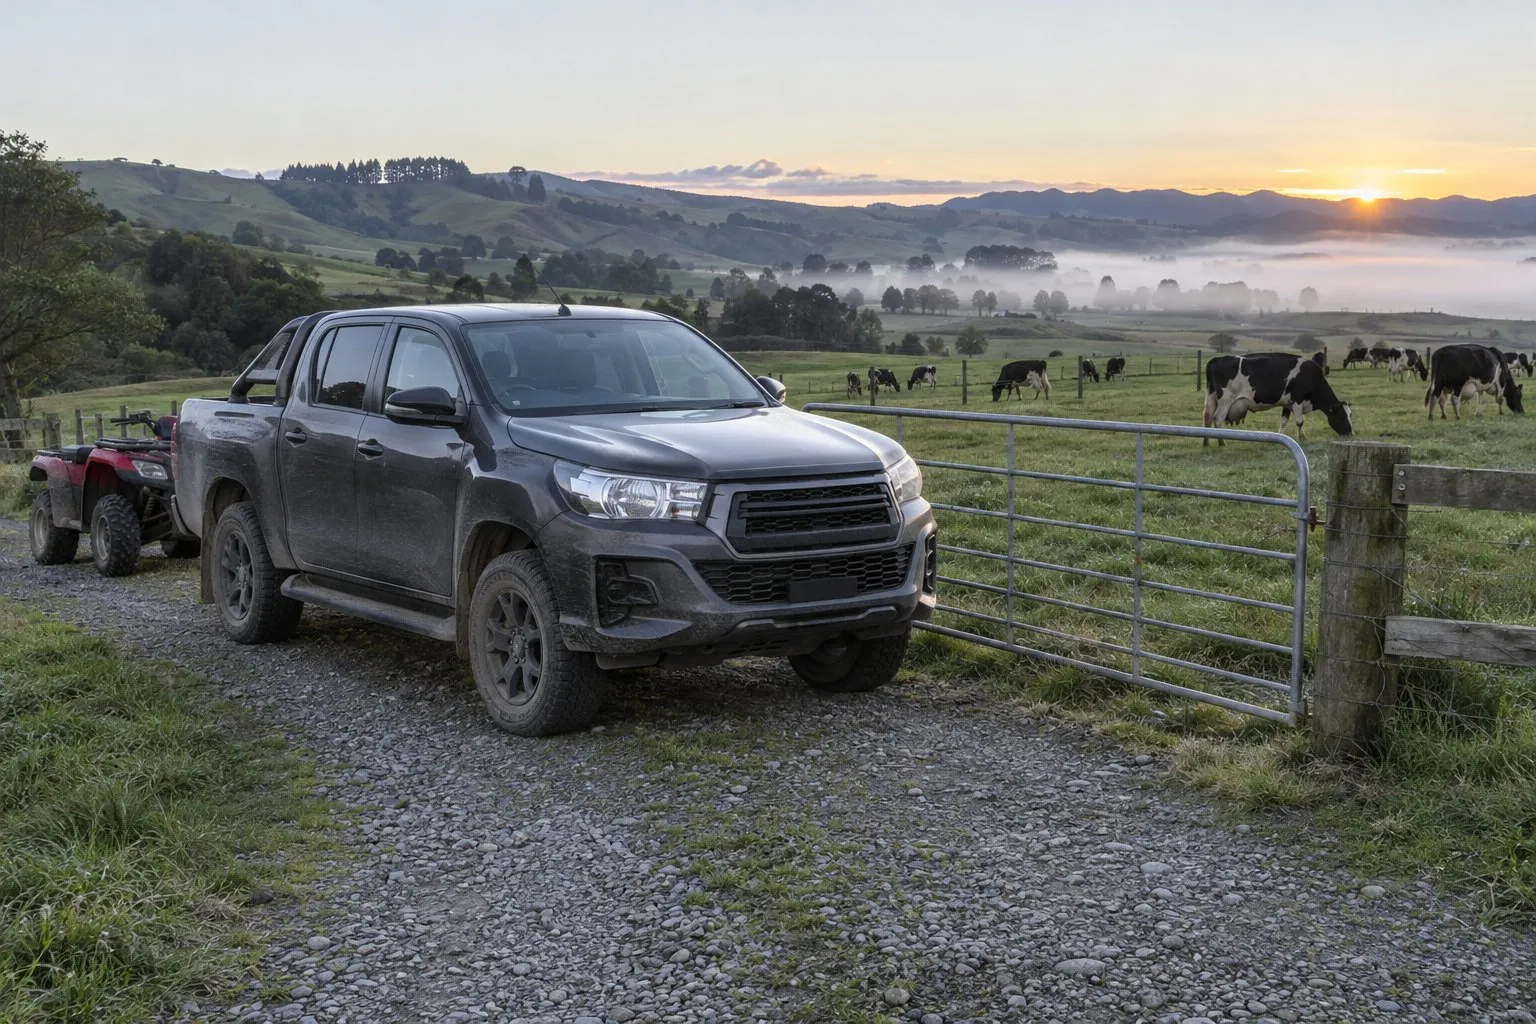
Tillen Finance is a New Zealand finance broker for farm utes, tractors, implements, machinery, quads, side-by-sides, trailers and horse floats. One short application goes to lenders on our panel who can assess seasonal farm income properly, every application is looked at case by case, and you usually have an answer within one business day.
- What we finance
- Utes, tractors, machinery, quads, side-by-sides, trailers, floats
- To enquire
- About 60 seconds, no impact on your credit score
- Answer
- Usually within one business day
- Assessed
- Case by case, on you, the asset and the lender
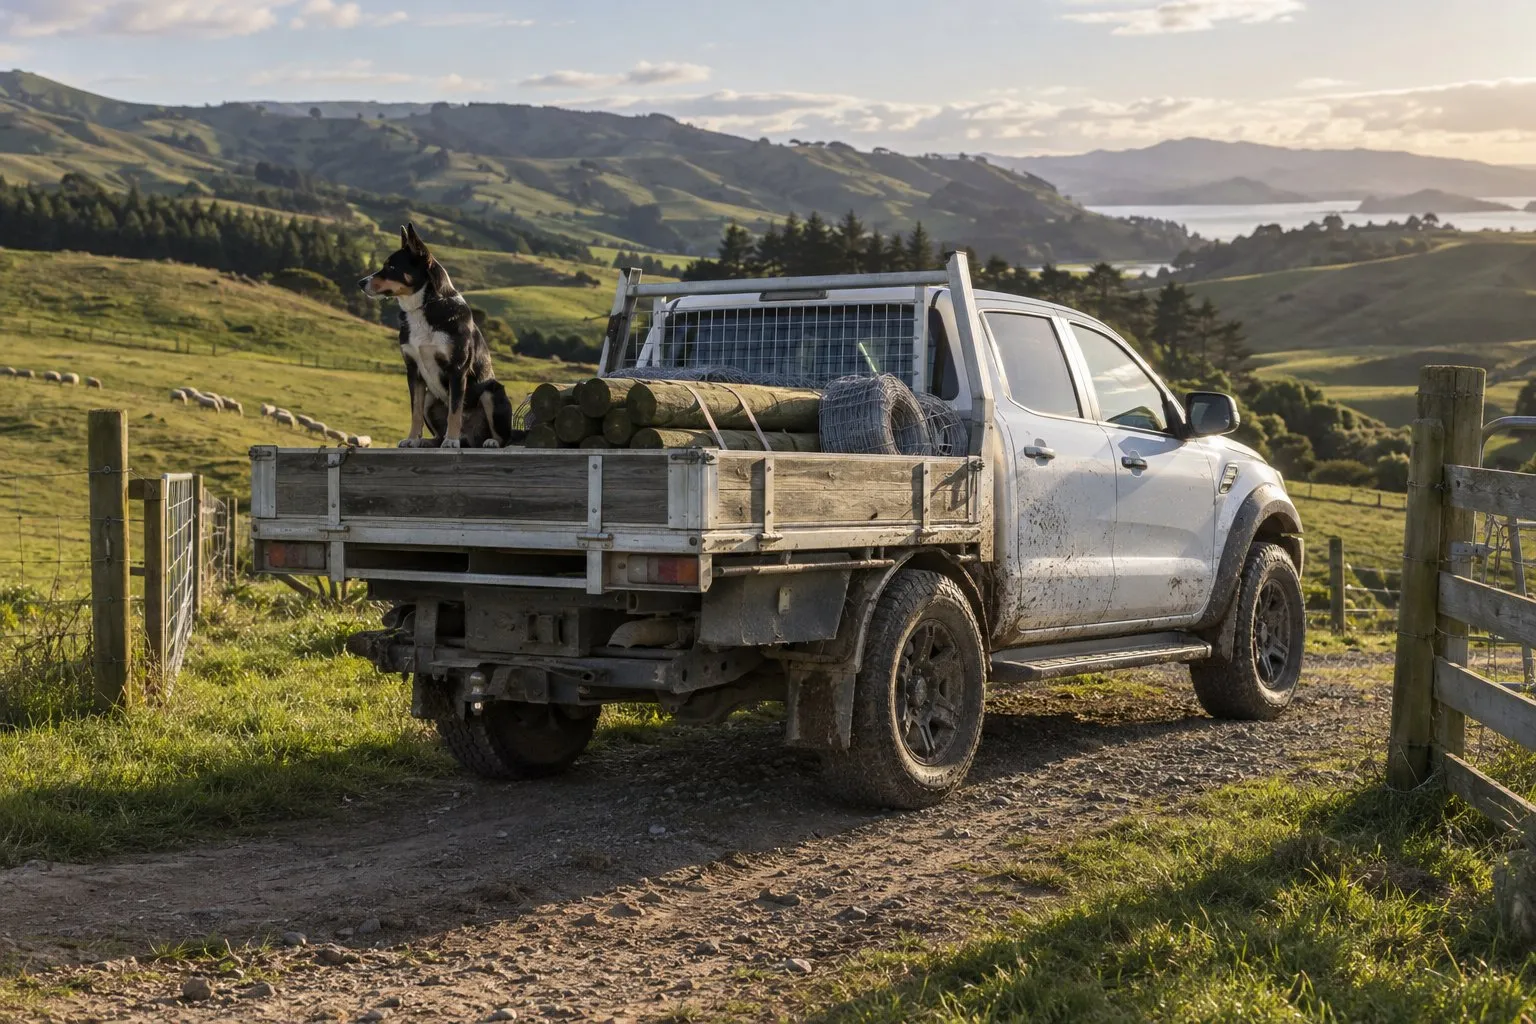
01
Why do farmers get knocked back on finance?
Most lending forms are built around a salary. Farm income is not: it follows the milk cheque, the works, the season and the weather, and a good year on paper can still look thin in the month someone happens to check.
A broker gets around that by taking your application to lenders who read the whole file, including business bank statements and your latest financial statements, and who are used to self-employed and seasonal earners.
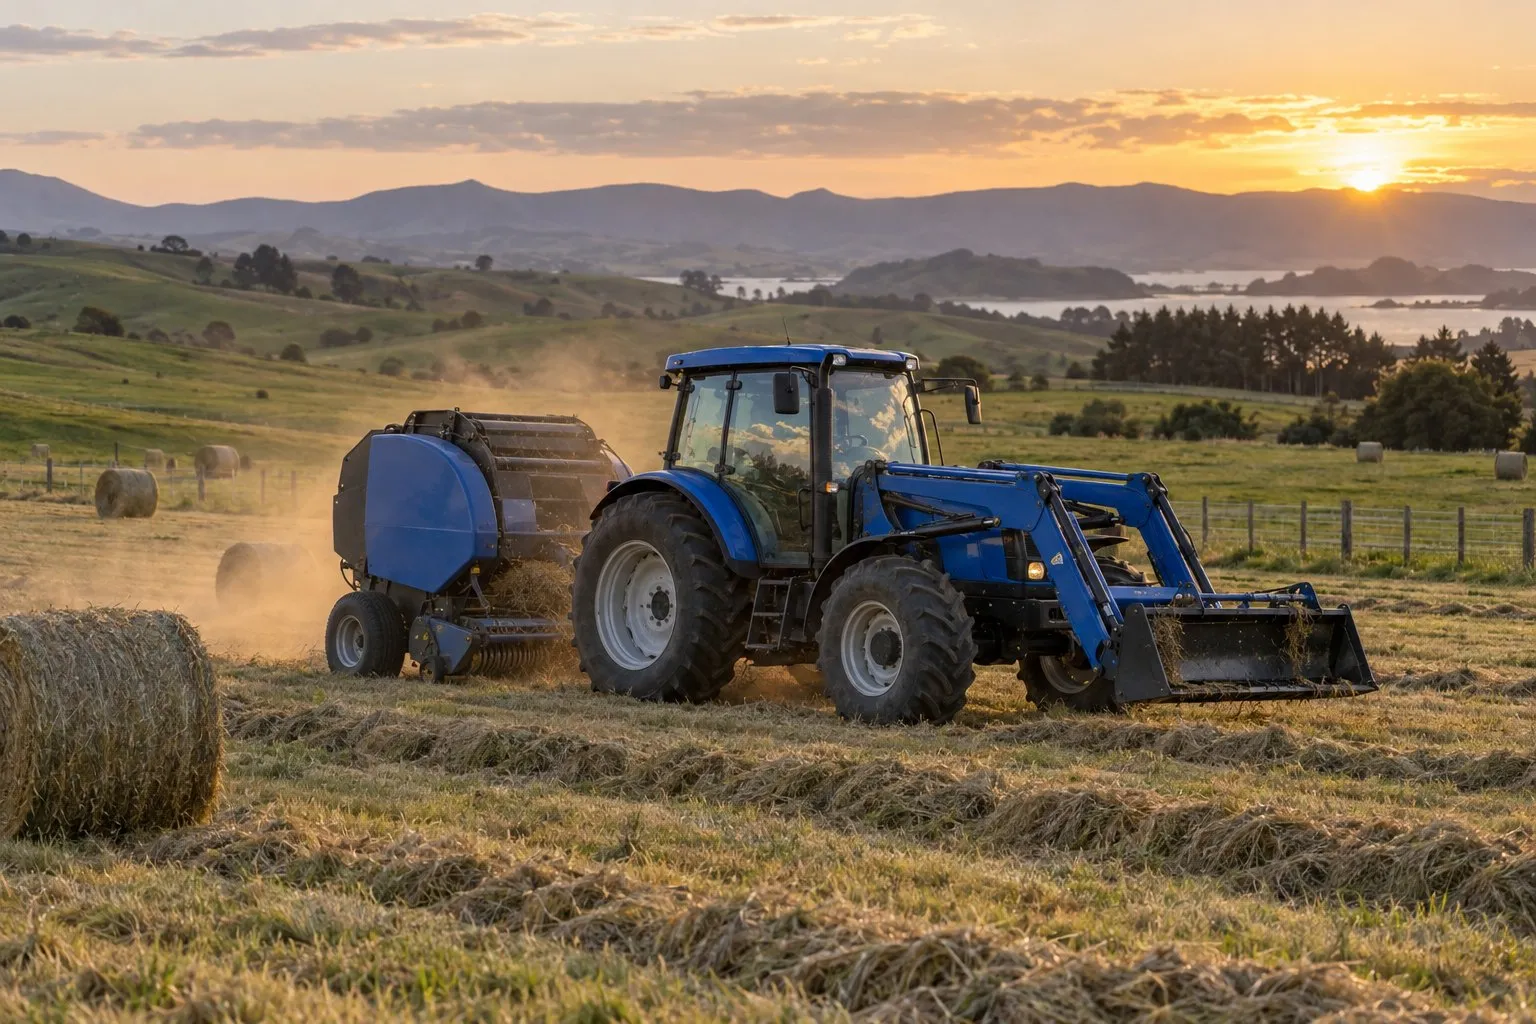
02
What can you finance?
We can consider all of these. Every application is assessed case by case, including the age of the gear, so there is no blanket age limit.
- Farm utes and 4WDs, new or used, from a dealer or a private seller
- Tractors, implements and other farm machinery
- Quad bikes, side-by-sides and farm bikes
- Stock trailers, general trailers and horse floats
- Work vehicles for rural contractors, fencers, shearers and agri-service businesses
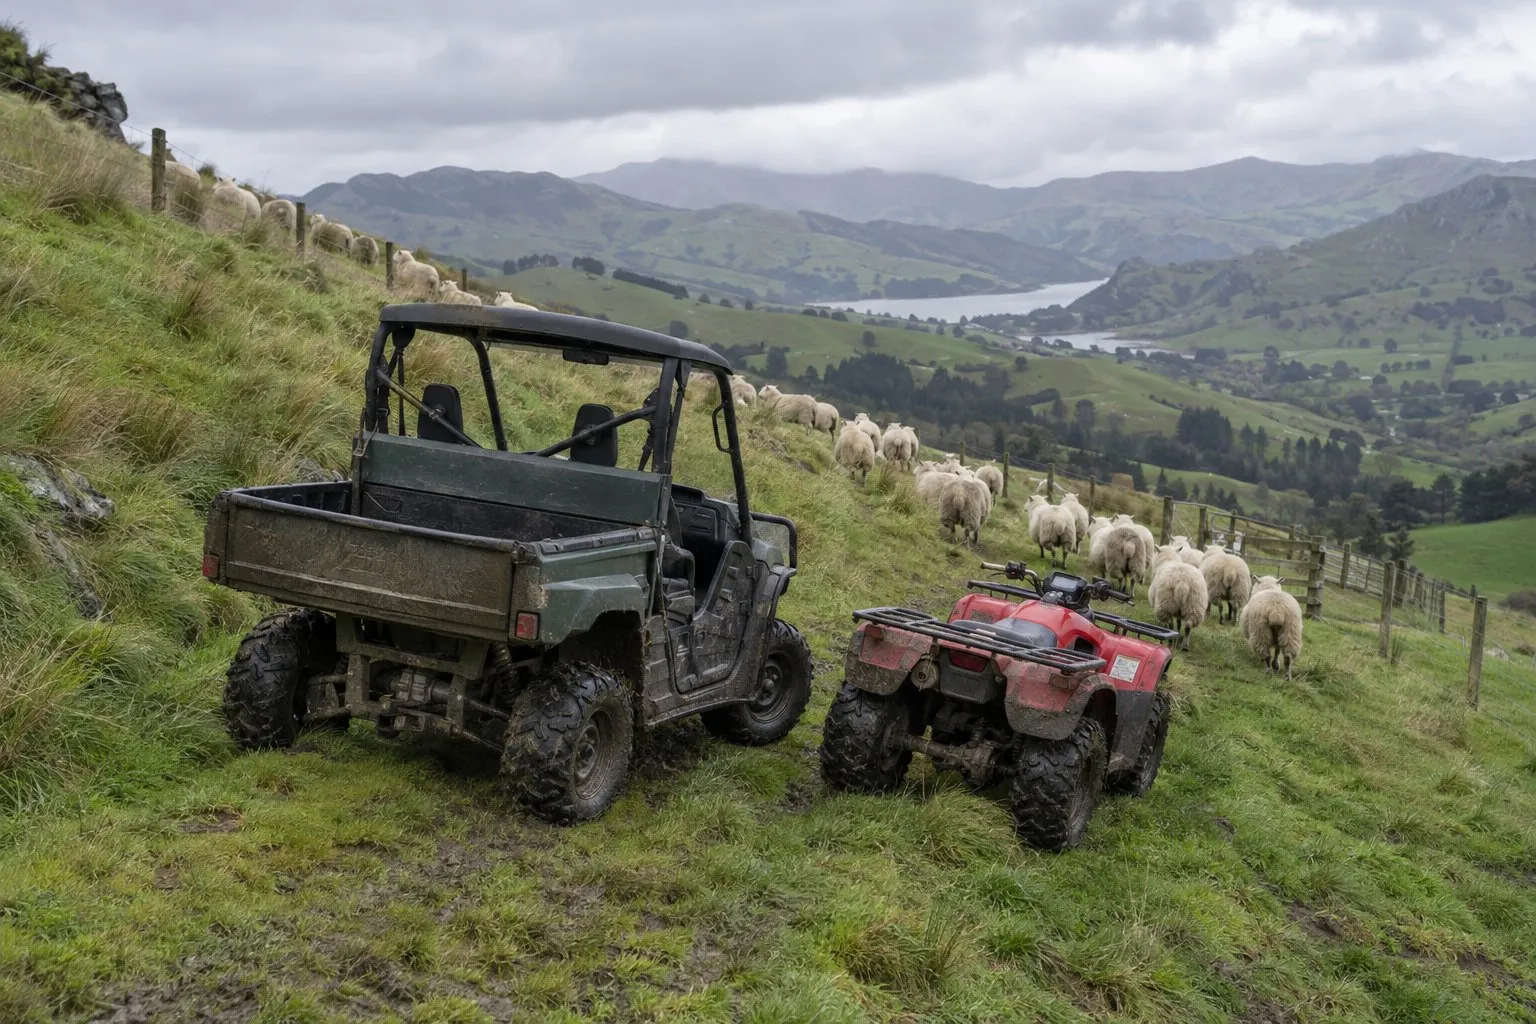
03
What paperwork does a farmer need?
For self-employed applicants it is usually three to six months of business bank statements plus your most recent IR3 or financial statements. Your accountant will already have these.
If you are GST-registered or buying through a company, partnership or trust, say so on the application. GST-registered buyers are welcome.
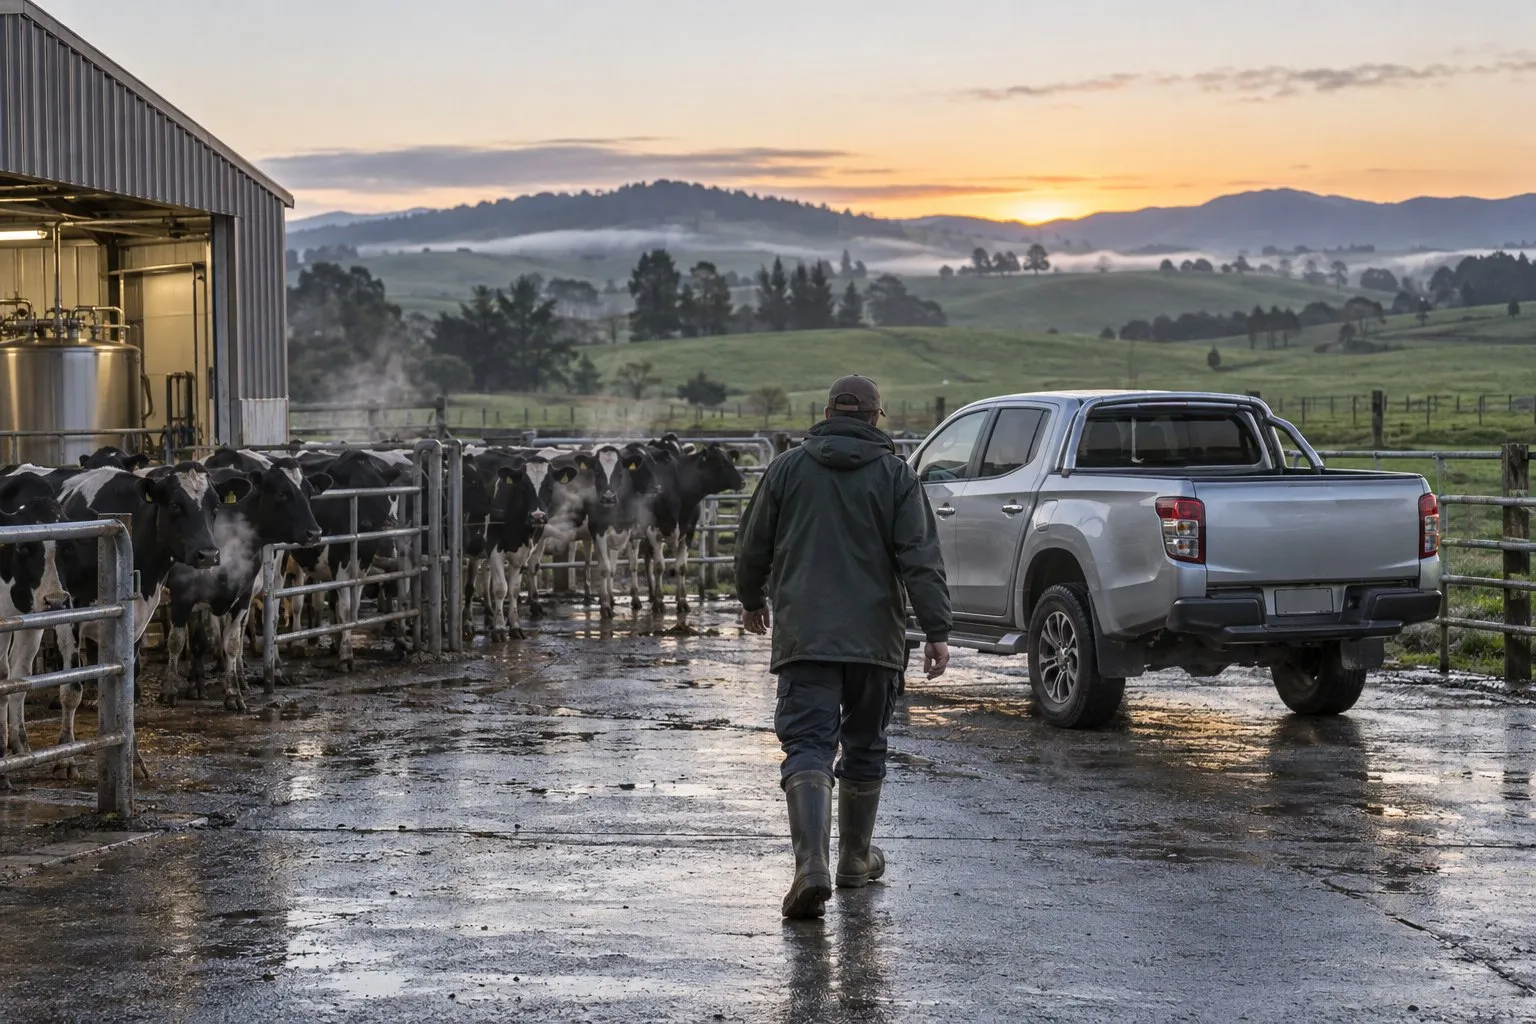
04
How does it work?
The loans are standard loans with regular repayments. Your seasonal income is assessed across the year, so the repayment needs to sit comfortably in the quiet months as well as the good ones.
- Enquire online in about 60 seconds. No impact on your credit score.
- Tyler calls you, usually the same day, to understand the farm and what you are buying.
- We compare suitable options across our panel and come back with what fits.
- You choose. Nothing is run against your credit file without your written consent.
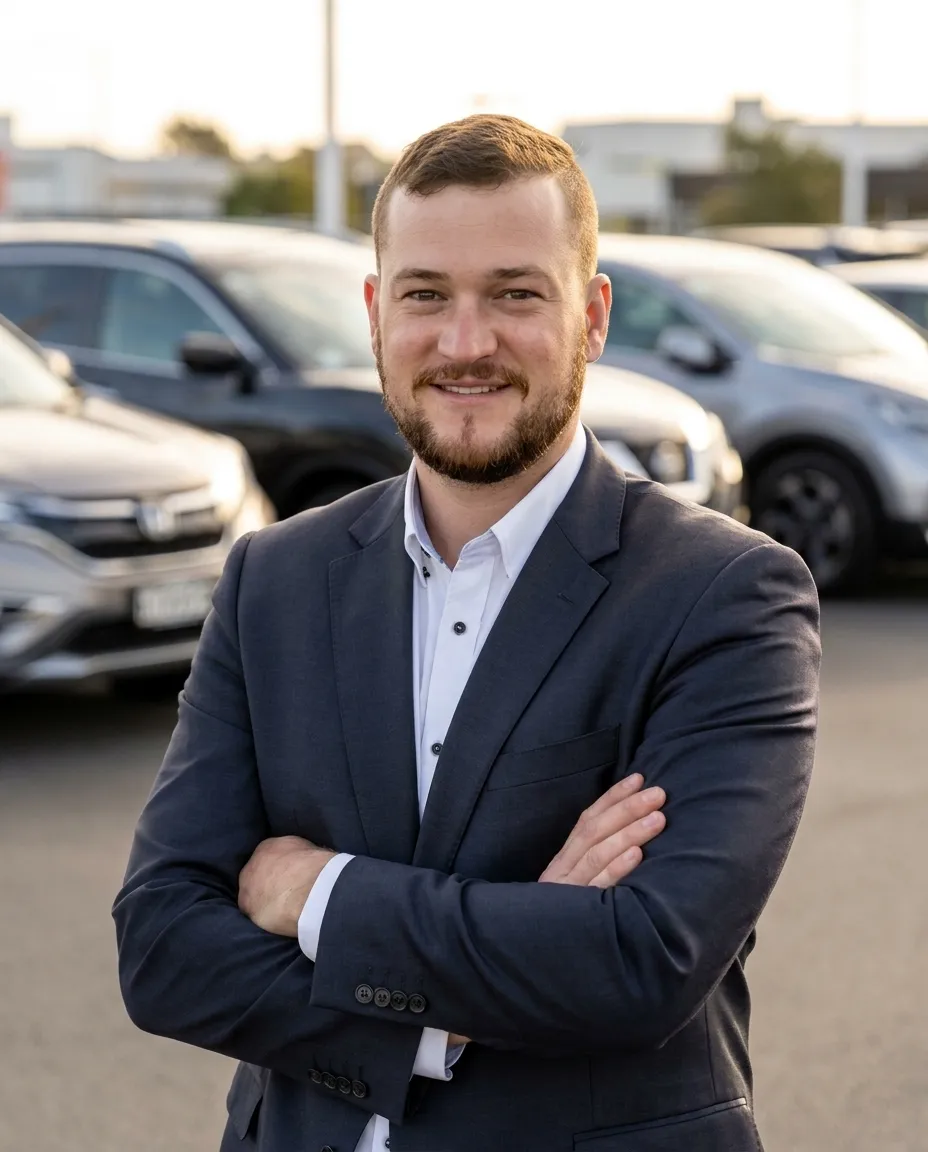
Meet your broker
A broker who knows the paddock, not just the paperwork.
I grew up on our family property in Dairy Flat, where we raised cows and sheep for homekill and did the processing ourselves. My cousin farmed sheep and weaners down in Pahiatua, and two of my uncles were farmers, one with a large sheep farm in Waikite and the other farming deer in Kamo. I’ve spent plenty of time in Red Bands stomping through paddocks.
Today I put that together with my automotive and finance experience. Farm income doesn’t arrive like a wage, and a form built around payslips often misses that. I read the whole picture, compare suitable options across our panel, and come back with what fits. No impact on your credit score to ask, and no commitment until you say yes.
Tyler Newman, Tillen Finance
Farm finance by what you are buying
Farm Ute Finance New or used utes and 4WDs for the farm, dealer or private sale. Tractor & Machinery Finance Tractors, implements and farm machinery, new or used. Quad & Side-by-Side Finance Farm bikes, quads, side-by-sides, trailers and horse floats. Sharemilker & Contractor Finance For people whose income is real but does not come as a payslip. Guides for farmers
Common questions
Can I get finance if my farm income is seasonal? +
Is there an age limit on the gear? +
Do I need a deposit? +
Will enquiring affect my credit score? +
What does it cost to use a broker? +
Apply in 60 seconds.
An initial enquiry with no impact on your credit score. No obligation. We’ll come back within one business day with your likely options.
- ✓ Specialist lenders compared in one go
- ✓ Self-employed and no-credit-history applicants welcome
- ✓ Likely options within one business day
- ✓ Real human broker, not a call centre
Prefer to chat?